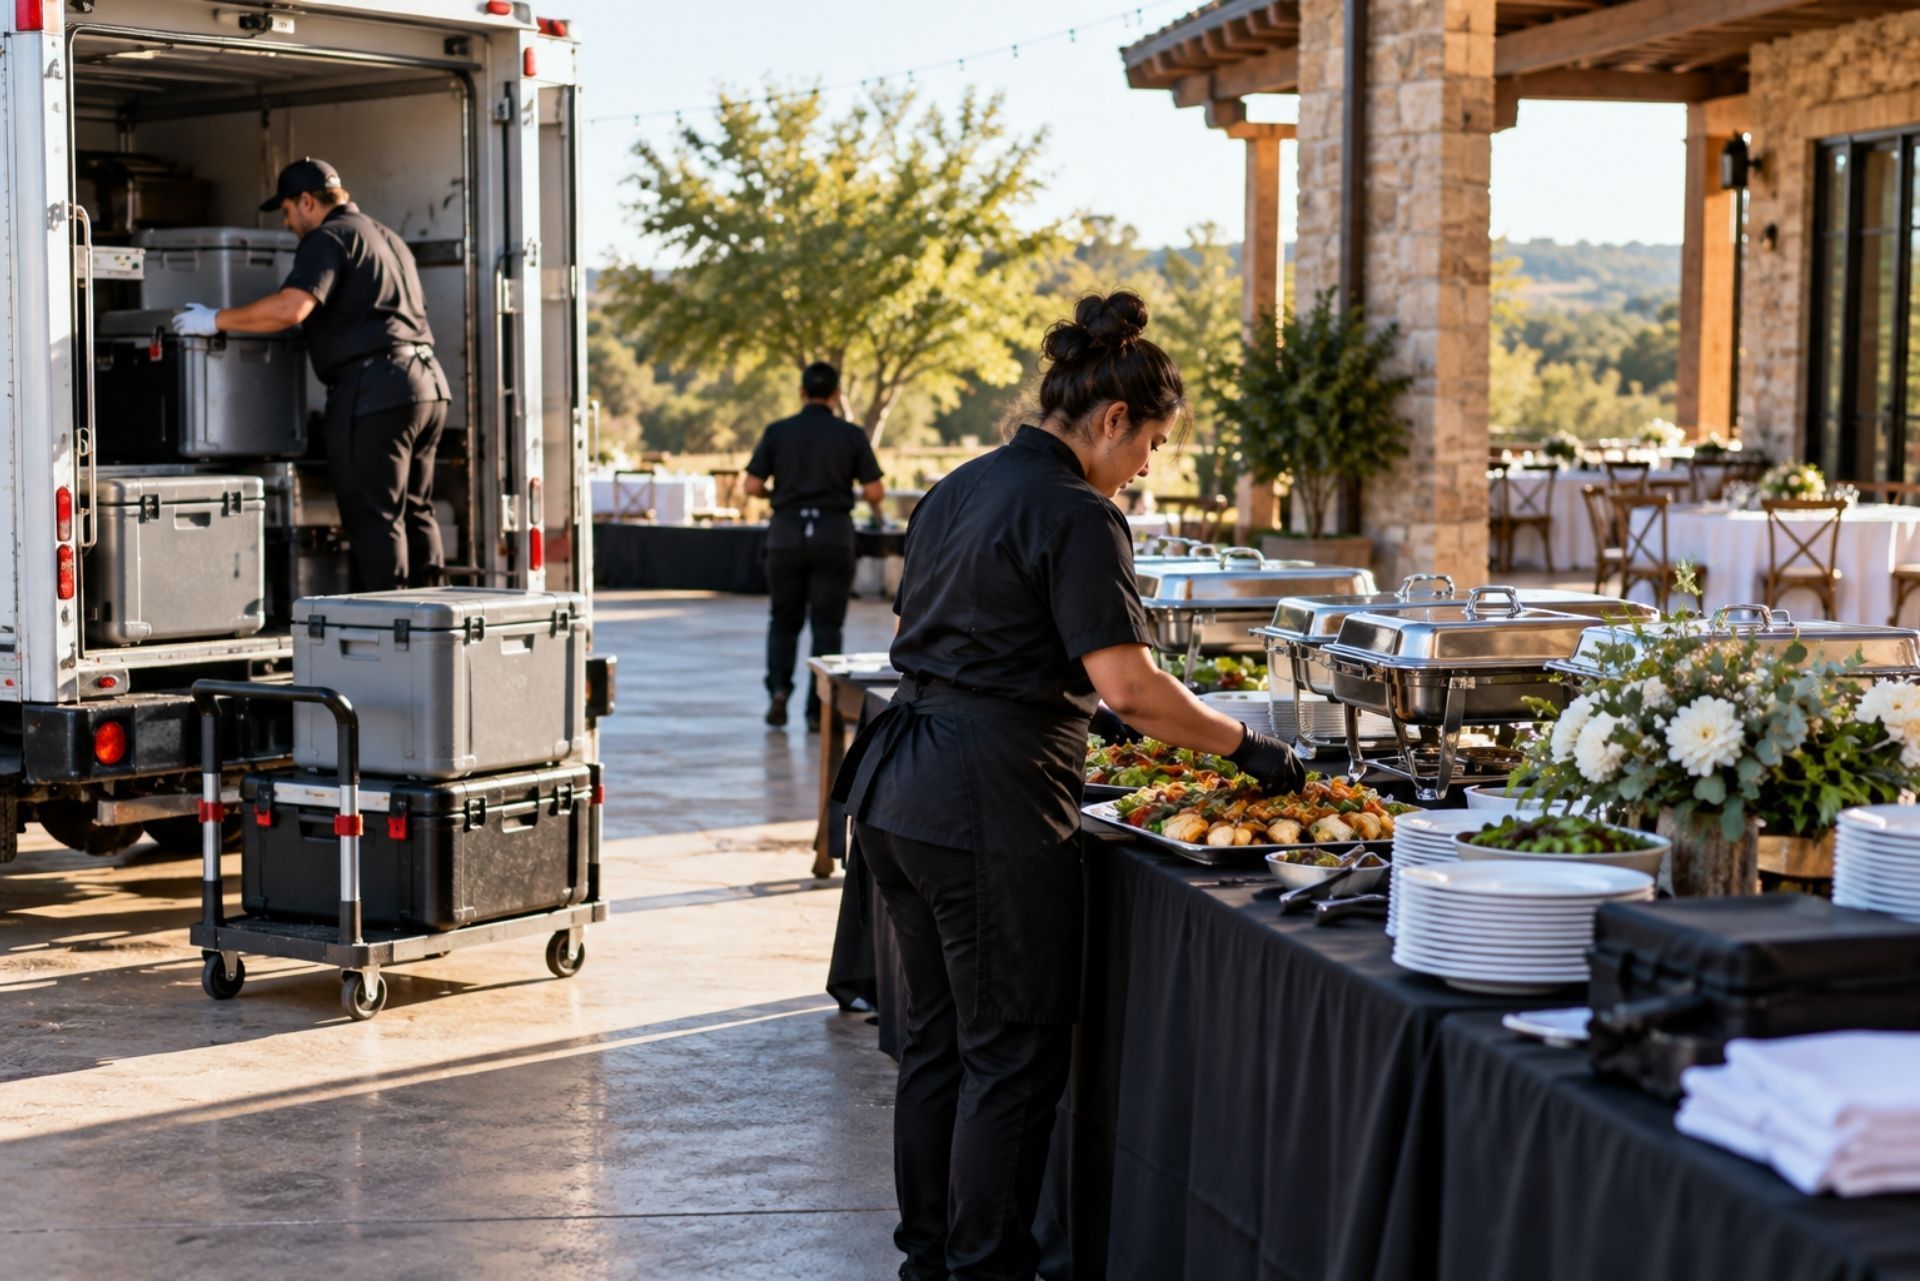
A single case of food poisoning at a corporate event can turn a thriving catering business into a legal nightmare overnight. One guest gets sick, posts about it online, and suddenly you're facing a lawsuit, a health department investigation, and a reputation crisis all at once. For Texas caterers, where the industry is growing faster than any other dining segment, the stakes have never been higher.
The right insurance setup is what separates a business that survives a bad week from one that closes permanently. But figuring out what coverage a Texas catering company actually needs, from liability and property to auto, cyber, and workers' compensation, isn't straightforward. Policies overlap, state laws have quirks, and the wrong gap in coverage can cost you everything. Texas has its own rules around workers' comp, health permits, and venue requirements that don't apply anywhere else.
This guide breaks down each type of coverage, what it actually protects, what it costs, and where caterers most commonly get burned. Whether you're running a two-person operation out of a commissary kitchen or managing a fleet of delivery vans across DFW, the goal here is simple: get you properly covered without overpaying.
Core Liability Protections for Texas Caterers
Liability insurance is the foundation of any catering insurance program. Without it, a single incident at an event can expose your personal assets, your business accounts, and your future earnings. Texas courts are not shy about awarding large judgments, and the food service industry generates more liability claims than most people expect.
General Liability and Slip-and-Fall Risks
General liability covers the basics: bodily injury, property damage, and personal injury claims that happen during your operations. Think of a guest tripping over a power cord at your buffet station, or your team accidentally damaging a venue's hardwood floors while setting up chafing dishes.
In Texas food service, general liability claims average around $30,000 per incident. That number climbs fast when medical bills, legal fees, and lost wages stack up. Most caterers should carry at least $1 million per occurrence with a $2 million aggregate, and many venues won't even let you through the door with less.
One thing to keep in mind: your general liability policy won't cover everything. It typically excludes auto accidents, employee injuries, and professional errors. That's why it's just one piece of the puzzle.
Product Liability: Handling Foodborne Illness Claims
Product liability is where catering gets specific. If someone claims they got sick from your food, this is the coverage that responds. It covers legal defense costs, settlements, and judgments related to foodborne illness, allergen exposure, or contaminated ingredients.
These claims are notoriously expensive because they often involve multiple plaintiffs. Serve bad shrimp at a 200-person wedding and you could face dozens of claims simultaneously. Your product liability coverage should be part of your general liability policy or added as a specific endorsement, and you need to confirm it explicitly covers food-related illness. Some generic policies have exclusions that leave caterers exposed.
Liquor Liability for Beverage Service
If you serve alcohol, even beer and wine at a casual event, you need liquor liability coverage. Texas holds alcohol servers responsible under its Dram Shop laws, meaning if an intoxicated guest causes an accident after your event, your company can be sued.
Standard general liability policies exclude alcohol-related claims. A separate liquor liability policy or endorsement fills that gap. Premiums vary based on your annual alcohol revenue and the types of events you serve, but skipping this coverage is a risk no caterer who pours drinks should take.
By: Linda Dodson
Agency Director at
Denton Business Insurance
Safeguarding Your Equipment and Assets
Your kitchen equipment, serving gear, and vehicles represent a serious investment. A single grease fire or van theft can wipe out tens of thousands of dollars in assets overnight. Property-related claims in Texas food service frequently exceed $100,000, so the right property coverage matters.
Commercial Property vs. Inland Marine Coverage
Commercial property insurance protects your equipment, inventory, and business contents at a fixed location, like your commissary kitchen or prep facility. But here's the catch: standard commercial property policies only cover items at the address listed on the policy.
Caterers don't work in one place. Your chafing dishes, portable ovens, and serving equipment travel to venues across the state. That's where inland marine coverage comes in. It protects your equipment in transit and at off-site locations. If you're loading $15,000 worth of gear into a van every weekend, inland marine isn't optional.
Many Texas caterers bundle their property and liability coverage into a Business Owner's Policy (BOP), which typically runs between $2,000 and $4,500 annually. A BOP is often the most cost-effective starting point, but make sure it includes or can be endorsed with inland marine, spoilage coverage, and equipment breakdown protection for refrigeration units.
Commercial Auto Insurance for Delivery Vans
If your business owns vehicles, commercial auto insurance is required by Texas law. The state minimum is $30,000/$60,000/$25,000 (bodily injury per person/per accident/property damage) according to amtexinsurance.com, but those minimums are dangerously low for a business. A serious accident with a loaded catering van can generate claims well beyond $60,000.
Most caterers should carry at least $500,000 in combined single-limit coverage. And if your employees ever use their personal vehicles for deliveries or event setup, you need Hired and Non-Owned Auto (HNOA) insurance. Personal auto policies exclude business use, so without HNOA, you're exposed every time a team member runs supplies in their own car.
Texas-Specific Legal and Labor Requirements
Texas has a few rules that trip up caterers who've done business in other states or who assume federal standards apply the same way here.
Workers' Compensation in the Lone Star State
Texas is the only state where private employers can opt out of workers' compensation entirely. That sounds like a cost savings, but the tradeoff is brutal. Non-subscribers lose three critical legal defenses in court: contributory negligence, assumption of risk, and fellow-employee negligence.
Translation: if an employee gets hurt on the job and you don't carry workers' comp, they can sue you directly, and you've already lost most of your legal leverage. For the 2025-2026 benefit year, the maximum weekly temporary income benefit is $1,271, which gives you a sense of the per-employee exposure.
Catering is physically demanding work. Burns, cuts, slips on wet kitchen floors, and lifting injuries are common. For most caterers with employees, carrying workers' comp is the smarter financial decision, even though it's technically optional.
Health Department and Venue Insurance Requirements
A major regulatory shift hit Texas on July 1, 2026: the state transitioned to a single statewide permit system for mobile food vendors and catering trucks through the Texas Department of State Health Services. This eliminated the old patchwork of city-by-city health permits, which is great news for caterers working across multiple Texas cities.
That said, most event venues still require proof of insurance before they'll book you. A standard certificate of insurance (COI) showing general liability with the venue listed as an additional insured is the norm. Some high-end venues require $2 million or more in coverage. If you're regularly working corporate events or weddings at upscale locations, your insurance limits need to match those requirements, or you'll lose bookings.
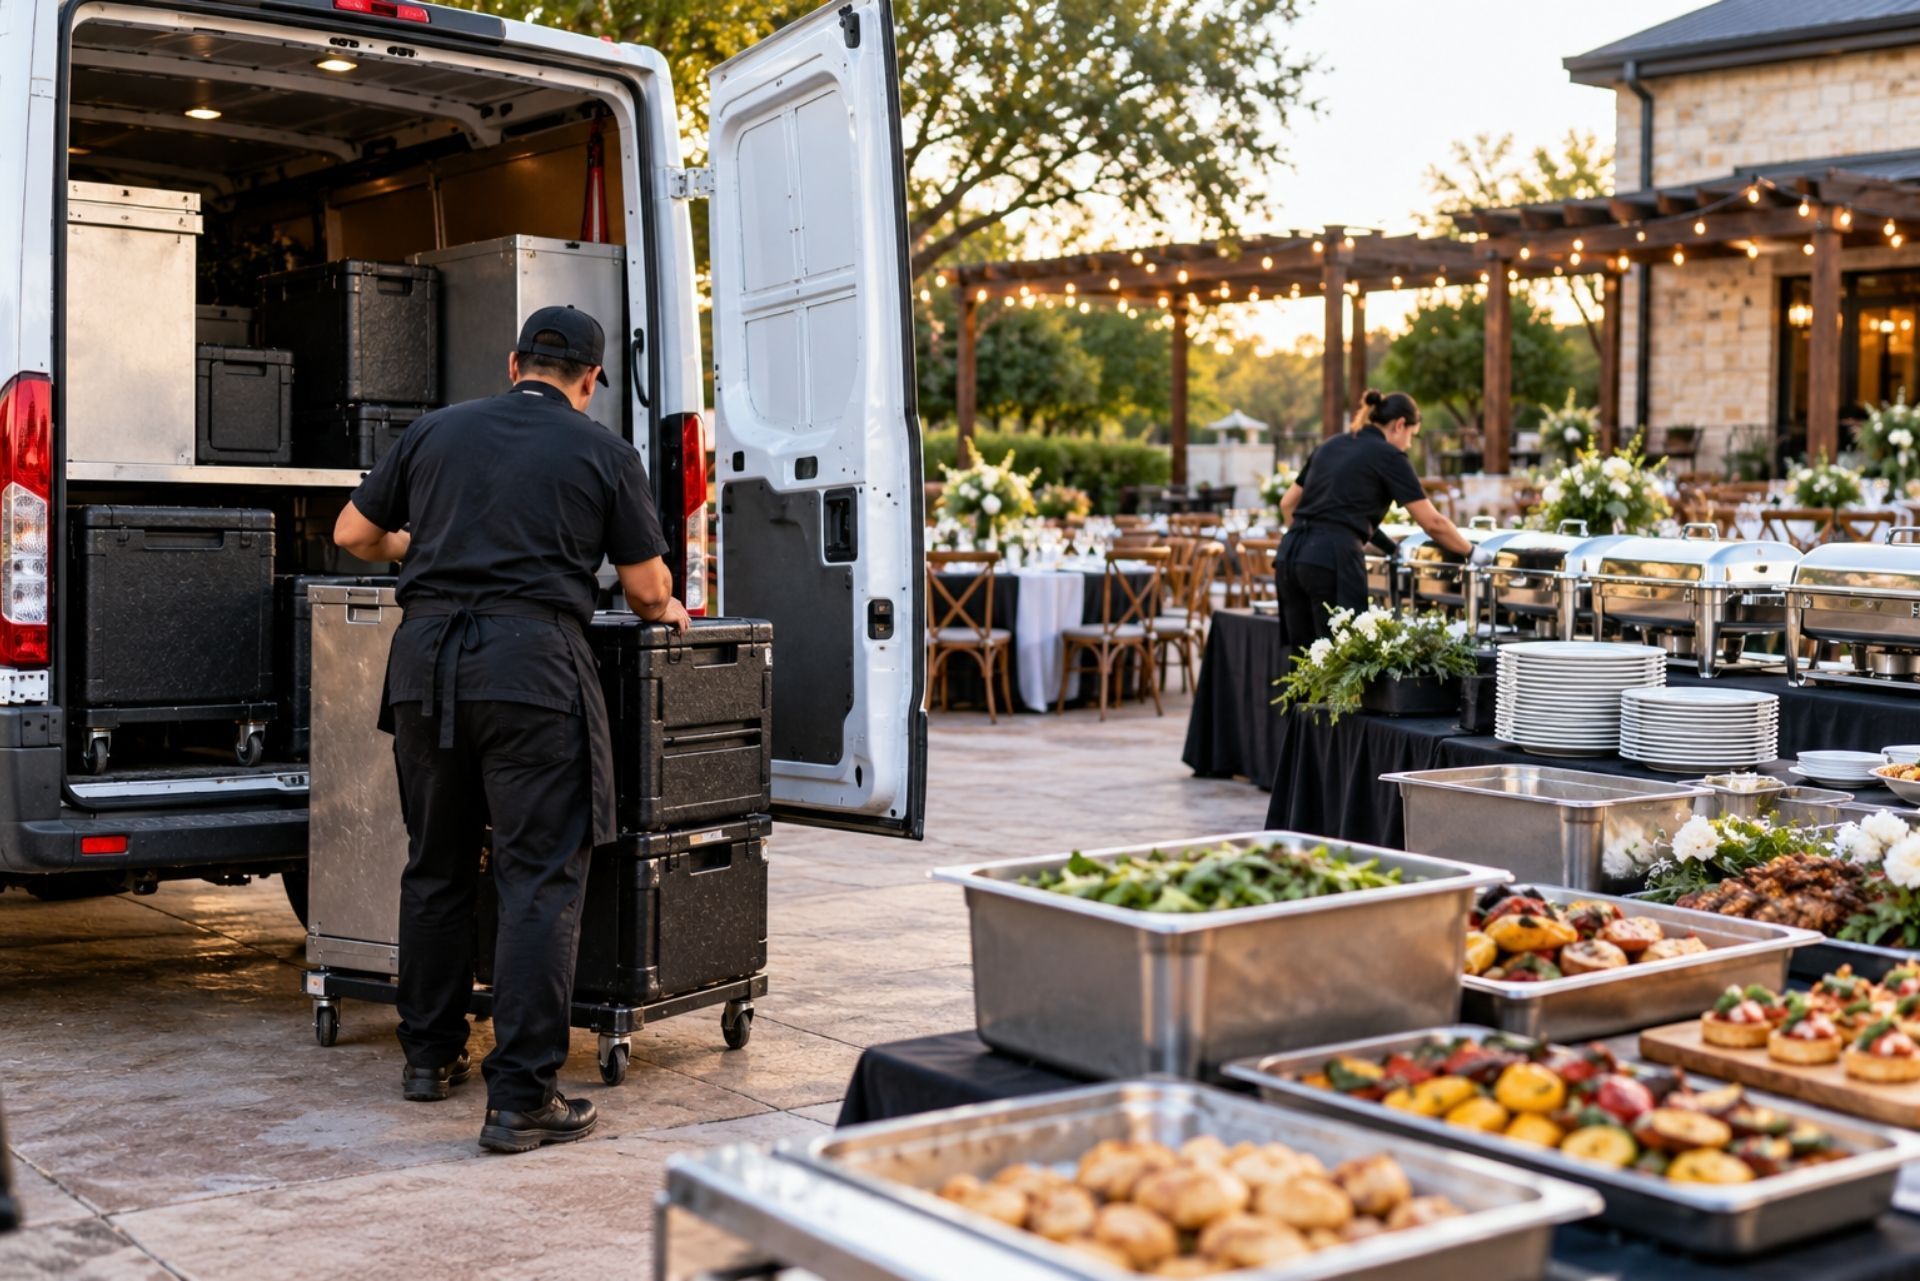
Comparison: Standard vs. Specialized Catering Coverage
Not all policies are built for caterers. A generic small business policy might leave critical gaps. Here's how standard coverage stacks up against specialized catering insurance:
| Coverage Area | Standard BOP | Specialized Catering Policy |
|---|---|---|
| General Liability | Included | Included |
| Product Liability (food) | Often excluded or limited | Explicitly included |
| Liquor Liability | Not included | Available as endorsement |
| Inland Marine (mobile equipment) | Not included | Available or included |
| Spoilage Coverage | Rarely included | Common endorsement |
| Equipment Breakdown | Sometimes included | Typically included |
| Cyber Liability | Not included | Available as endorsement |
| HNOA Auto | Not included | Available as endorsement |
An independent agency like Denton Business Insurance can compare policies across carriers like Nationwide, Travelers, and Chubb to find coverage built specifically for food service operations. The difference between a generic BOP and a properly tailored catering policy can be the difference between a covered claim and a denial letter.
One area that often gets overlooked is cyber liability. If you process credit card payments through a POS system or accept online orders, you're handling sensitive customer data. A data breach or ransomware attack can trigger notification requirements, legal costs, and regulatory fines. Cyber liability coverage addresses these risks, and it's increasingly relevant as caterers integrate with third-party ordering and delivery platforms.
Common Questions About Catering Insurance
Frequently Asked Questions
How much does catering insurance cost in Texas? A Business Owner's Policy for a Texas catering company typically costs between $2,000 and $4,500 per year. Your actual premium depends on revenue, number of employees, whether you serve alcohol, and the types of events you work.
Do I need workers' comp if I only have a few employees? Texas doesn't require it regardless of size, but going without it means you lose major legal protections if an employee sues. For most caterers, even small ones, carrying workers' comp is the safer bet.
What if a venue requires more coverage than I currently carry? You can usually increase your limits or add the venue as an additional insured by contacting your agent. At Denton Business Insurance, we handle these certificate requests regularly and can often turn them around the same day.
Does my personal auto policy cover catering deliveries? No. Personal auto policies exclude business use. You need either a commercial auto policy or HNOA coverage to protect your business when vehicles are used for deliveries or event setup.
Is cyber insurance really necessary for a catering company? If you process credit cards, store customer data, or use online ordering platforms, yes. A single data breach can cost tens of thousands in notification and legal expenses, far more than the annual premium for a cyber policy.
What changed with the new Texas mobile food vendor permit in 2026? Texas now issues a single statewide permit through the Department of State Health Services, replacing the old system where you needed separate permits for each city. This simplifies compliance for caterers operating across multiple locations.
The catering industry in Texas is booming, but rising costs are a real pressure point. Insurance premiums are climbing alongside food costs that have increased significantly since the pandemic, making it more important than ever to get the right coverage without overpaying.
Start by auditing your current policies against the coverage types outlined here: general liability, product liability, liquor liability, commercial property, inland marine, commercial auto, HNOA, workers' comp, and cyber. If you find gaps, or if you're not sure whether your existing policy actually covers food-related claims, that's your signal to talk to someone who specializes in this.
Denton Business Insurance works with caterers across Texas and shops multiple carriers to find coverage that fits your specific operation. Whether you need a COI for a venue by Friday or a full policy review, reach out for a no-obligation quote. Getting this right now means you can focus on growing your business instead of worrying about what happens when something goes wrong.
Straight from the Clients We Serve
Texas Business Owners Rate Us 5 Stars — Here Is Why
We hear the same things repeatedly: fast service, honest advice, and coverage that made sense for their situation. That is what we aim for every time.

Protection Across Every Area of Your BUSINESS
What Texas Businesses Need. What We Deliver.
From your job site and your fleet to your data and your payroll — we cover the risks that Texas businesses carry every day.
General Liability
Covers third-party claims of bodily injury, property damage, and advertising injury. A foundational protection for nearly every Texas business, regardless of industry or size.
Commercial Property
Covers your building, equipment, inventory, and business contents against fire, theft, storms, and vandalism. Can also include lost income if your businesses are forced to stop.
Commercial Auto
Protects vehicles your company owns, leases, or uses for work. Covers liability, collision damage, and injuries for employees driving on company time.
Errors & Omissions
Protects service providers when a client claims your advice, work, or recommendations caused them a financial loss. Critical for consultants, IT firms, agents, and other professional service businesses.
Directors & Officers
Covers leadership decisions that result in claims from employees, investors, or outside parties. Protects your directors and officers personally when management decisions are challenged.
Inland Marine & Equipment Floater
Covers tools, materials, and equipment that move between job sites or are stored off your primary property. Fills the gap where a standard commercial property policy stops.
Every Sector Has Its Own Risk Profile
We Know Your Trade. We Know Your Exposure.
We work with a wide range of Texas industries — each with different coverage priorities. Below are the sectors we serve most often.
Apartment Complexes
Texas apartment owners face liability across common areas, tenant incidents, and on-site staff. We cover your property, your income, and your exposure — across one complex or an entire portfolio.
Manufacturing Businesses
Equipment breakdowns, product liability, and workforce injuries are daily risks for Texas manufacturers. We build coverage from the shop floor to the loading dock — so one incident does not shut you down.
Artisan Contractors
Plumbers, electricians, and skilled tradespeople work in high-risk environments every day. We build coverage around your tools, your vehicles, and your crew — so a job site incident does not stop your business.
Restaurants & Food Service
Restaurants carry liability on every shift — from the kitchen to the dining room and everything in between. We protect your location, your staff, and your equipment, including lost income when operations stop.
Non-Profits Service
Non-profits face unique liability across events, volunteers, staff, and leadership decisions. We cover your organization from the ground up — so you can focus on your mission, not your exposure.
Event Insurance
Event organizers face liability the moment guests arrive, vendors set up, and alcohol is served. We cover your event from start to finish — so one unexpected incident does not cancel everything you planned for.
Answers Before You Pick Up the Phone
What Texas Businesses Ask Us Most
We get a lot of the same questions from business owners across Texas. Here are honest answers to the ones that come up most.
What information do you need to get a commercial insurance quote?
We keep the process straightforward. We typically need your business name, a description of your operations, your gross annual sales projection, number of full-time and part-time employees, your gross annual payroll, and the types of coverage you are looking for. If you have an existing policy, the expiration date and current carrier help us put together a competitive comparison.
The most important thing you can do is be transparent about what your business actually does. Accurate classification ensures you have real coverage if a claim occurs. We have seen businesses with active policies that were incorrectly classified — and those gaps only surface at the worst possible moment.
Does Texas require businesses to carry Workers' Compensation Insurance?
Texas is the only state in the country that does not require most private employers to carry Workers' Compensation. However, if your business holds government contracts or works as a subcontractor on a job site, the hiring company will almost always require proof of coverage before work begins. A growing number of general contractors across Denton and the DFW area enforce this as a standard condition.
Even without a legal requirement, carrying Workers' Comp protects your business from direct liability if an employee is hurt on the job. Medical bills, lost wages, and legal fees can add up quickly — and one serious incident can create a financial loss that far exceeds years of premium payments.
What is a commercial insurance audit and should I expect one?
Most commercial general liability policies are auditable. At the end of your policy term, the insurance carrier reviews your actual gross sales to make sure your premium matched your real exposure. If your sales grew during the year, you may owe an additional premium. If sales came in lower, you could receive a refund.
The best way to avoid a large balance due at audit time is to update your projected gross sales with us during the year if your business grows faster than expected. We can endorse your policy mid-term to reflect the change and spread any additional premium across smaller installments instead of one lump sum at year-end.
What factors affect how much my commercial coverage will cost?
Your premium is calculated based on several variables specific to your operation — industry classification, gross annual sales, number of employees, gross payroll, claims history, and the types of coverage you need. A business that handles physical work with a crew on job sites will pay differently than a professional services firm working out of an office.
As an independent agency, we compare quotes across multiple carriers — including Travelers, The Hartford, Chubb, AmTrust, and others — to find the combination of coverage and price that works for your situation. There is no obligation after your quote, and we walk through every option in plain terms before you decide anything.
My business is a restaurant — what coverage do I actually need?
Restaurants are not a one-size-fits-all class of risk. Carriers look at a range of factors when evaluating a restaurant account: whether you serve alcohol, whether deep frying is involved, the type of fire suppression system in place, whether you have a hood cleaning contract, and whether you offer catering, delivery, or live entertainment. All of these affect both pricing and carrier appetite.
A well-structured restaurant policy typically includes general liability, building and business personal property coverage, liquor liability if applicable, food contamination coverage, business income protection, and workers' compensation for your staff. We work with carriers that actively want to write restaurant accounts in Texas — including Travelers, The Hartford, and Chubb — so you have real options to compare.
Can you help insure a business that is hard to place or outside the mainstream?
Yes — this is one of our strengths. We work with Excess and Surplus (E&S) lines markets through carriers like Burns & Wilcox for businesses that standard carriers will not write. We have placed coverage for master sign electricians, cable splicing operations, transmission rebuild shops for classic cars, CBD retailers, and many other non-standard accounts.
If you have been told your business is difficult to insure or you have received very limited options in the marketplace, reach out to us. We take time to understand your operations in detail, present your account to the right markets, and work to find coverage that actually reflects what you do — not a generic policy that leaves gaps.
Still have Question?
We’re here to help you!
Written for the Texas Business Owner
Insights That Help You Make Smarter Decisions
We publish articles on real topics that affect how Texas operators get covered — from local regulatory updates to coverage gaps most owners do not know they have.
Contact Us