Texas Pressure Washing Franchise Insurance

See How We're Different
Call Us: (940) 268-5112
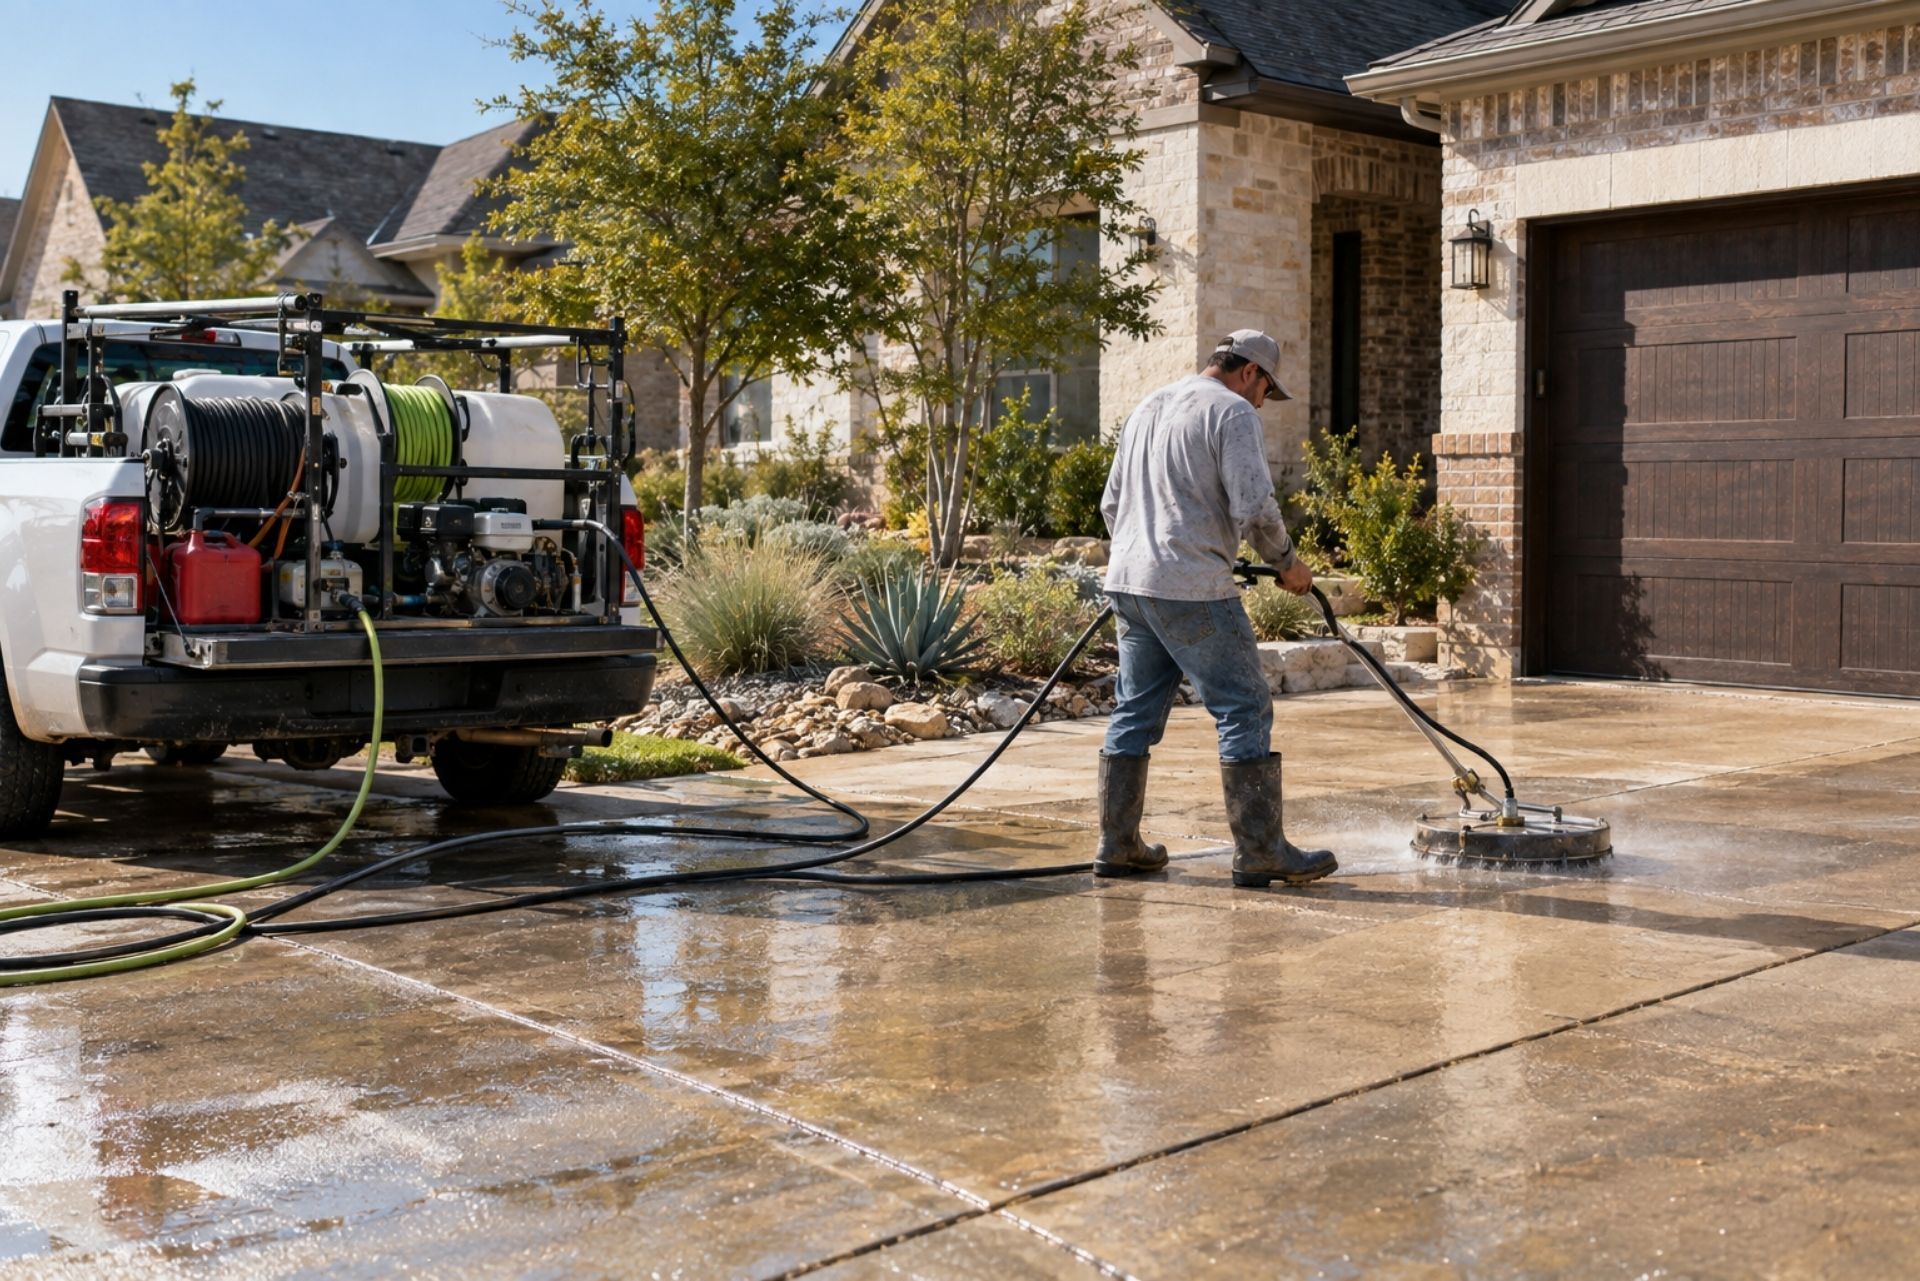
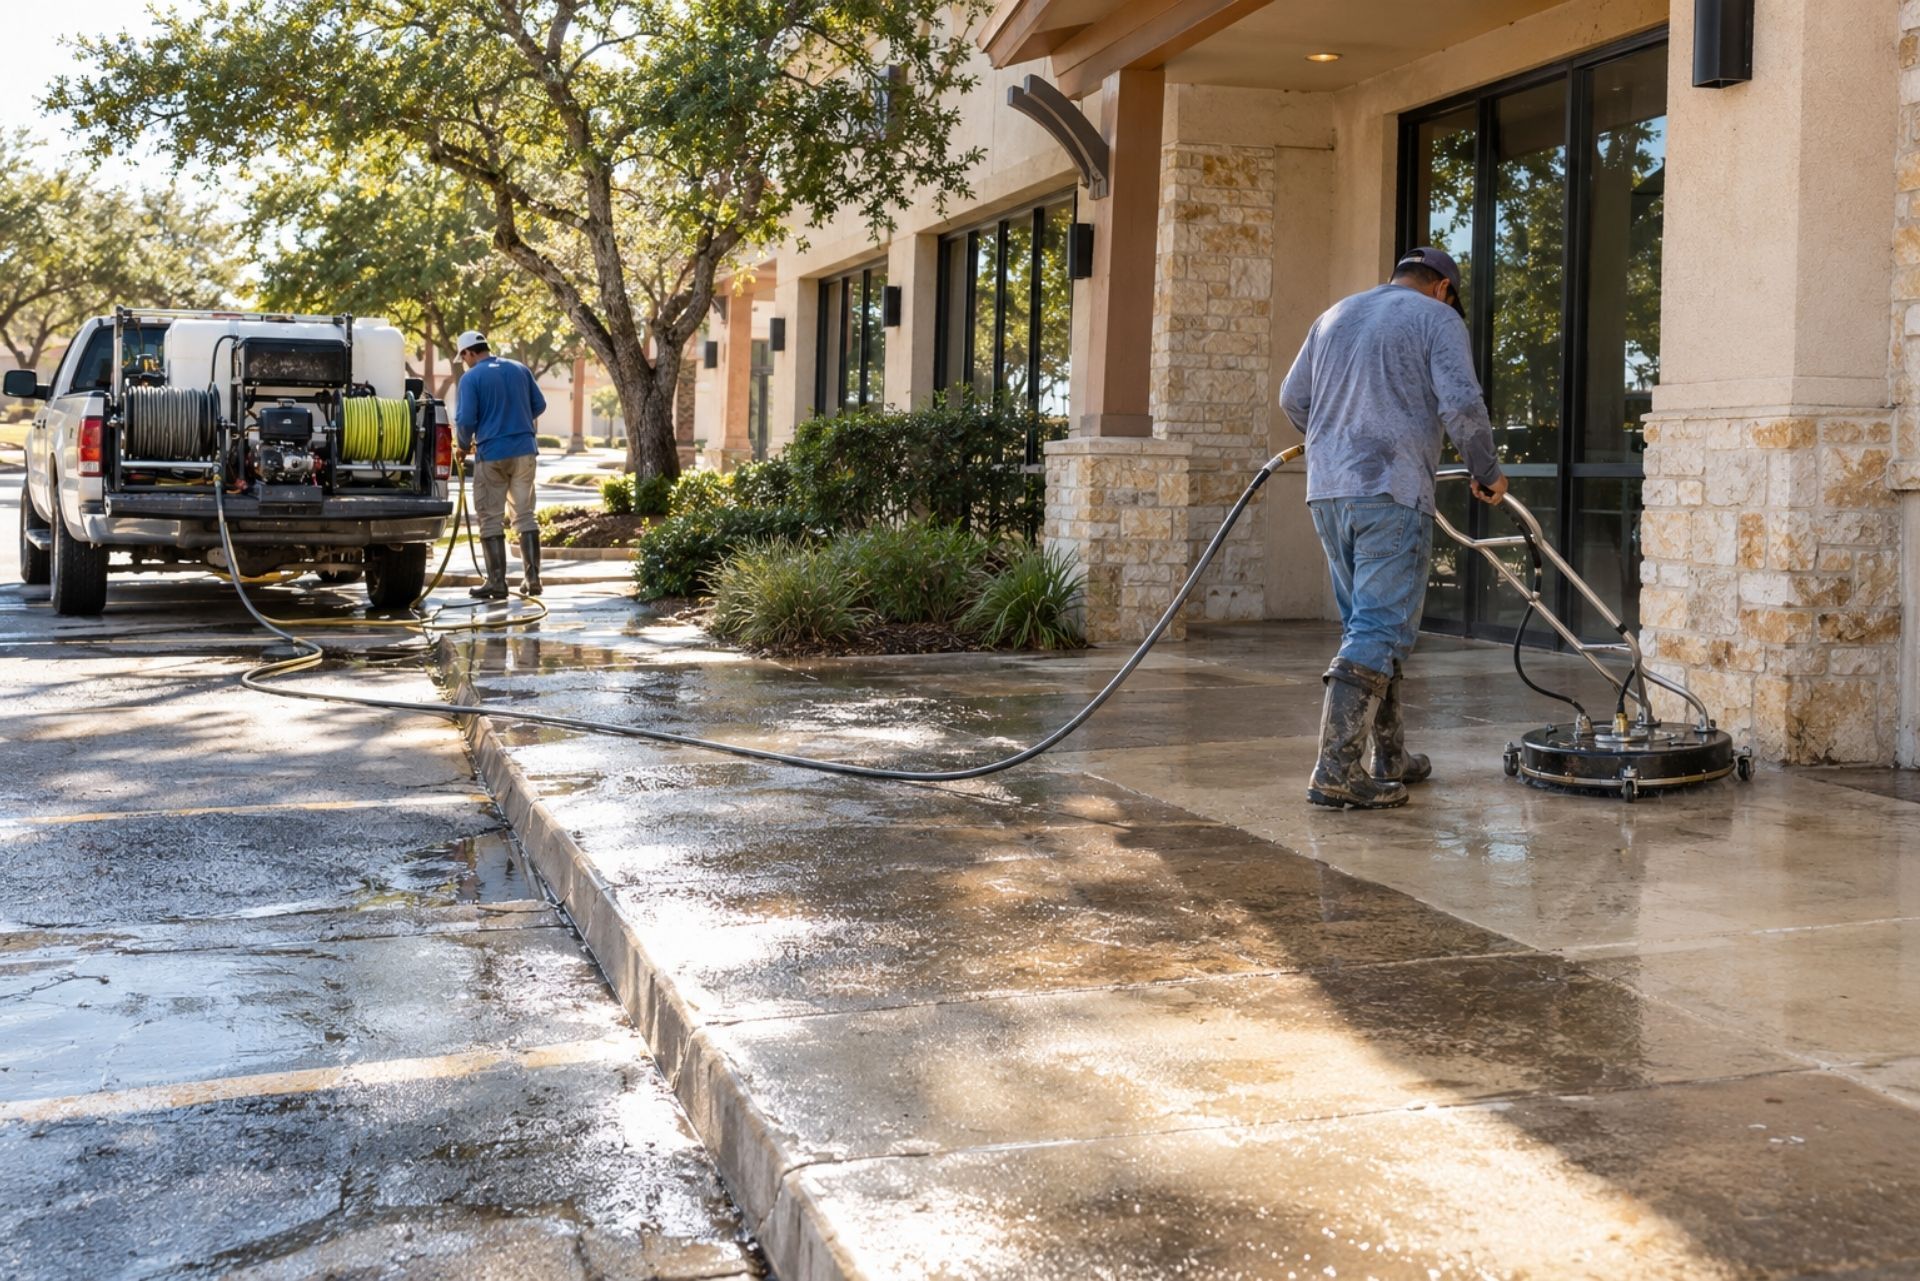
A crew finishes blasting grime off a commercial storefront in Plano, and the property manager calls the next morning: the cleaning solution stained the decorative stonework, and two customers slipped on runoff that pooled near the entrance. The franchise owner is staring at a five-figure repair bill, a potential injury claim, and a franchisor demanding proof of coverage by end of week. This is the kind of scenario that separates a well-insured pressure washing franchise from one that's suddenly fighting for survival.
If you're opening or already running a pressure washing franchise in Texas, the insurance question isn't simple. Your franchisor has requirements. The state has its own rules. And the nature of the work, high-pressure water, chemical detergents, heavy mobile equipment, and constant proximity to other people's property, creates a risk profile that generic small-business coverage won't fully address. The coverage you need spans liability, property, auto, cyber, and workers' compensation, and each piece serves a distinct purpose. Getting any one of them wrong can leave a gap that costs far more than the premium you saved.
This guide breaks down what a Texas pressure washing franchise actually needs, why each policy matters, and how to structure coverage that satisfies both your franchisor and your own
financial protection.
Core Insurance Requirements for Texas Pressure Washing Businesses
Every pressure washing operation shares a baseline set of risks: you're working on someone else's property, hauling equipment on public roads, and often employing a crew that handles powerful machinery. These three realities drive the core insurance requirements that no franchise should operate without.
The tricky part is that "core" doesn't mean "basic." Each of these policies has nuances specific to pressure washing that a general insurance quote might miss entirely. A policy written for a consulting firm or a retail shop won't account for the chemical exposure, surface damage, or vehicle-mounted equipment that define your daily operations.
General Liability for Property Damage and Bodily Injury
General liability is the foundation. It covers third-party bodily injury and property damage, the two most common claim types in pressure washing. A pedestrian slips on wet pavement outside a restaurant you just cleaned, or your technician's wand gouges a wooden deck: general liability responds to both.
Texas pressure washing businesses typically pay around $75 per month for standard $1M per occurrence and $2M aggregate limits. That's roughly $895 per year, which is modest given the exposure. One thing to keep in mind: standard GL policies often contain a "Your Work" exclusion that excludes damage to the specific surface you were hired to clean. If you etch a client's driveway while cleaning it, your policy may deny that particular claim unless you've addressed this gap with an endorsement.
At Denton Business Insurance, we regularly see franchise owners who assumed their GL policy covered everything, only to discover the "Your Work" exclusion during a claim. It's one of the first things we check when reviewing a pressure washing policy.
Texas Workers' Compensation Rules for Franchise Owners
Texas stands alone as the only state where private employers aren't required to carry workers' compensation insurance. That sounds like a cost-saving opportunity, but the reality is more complicated for franchise owners.
Going without workers' comp (called being a "non-subscriber") means you lose several legal protections. Injured employees can sue you directly, and you can't use common defenses like contributory negligence. For a pressure washing crew handling 4,000 PSI equipment and climbing ladders daily, the injury risk is real: burns, falls, repetitive strain, and chemical exposure are all documented hazards.
Most franchisors require workers' comp regardless of Texas law. Even if yours doesn't, the liability math usually favors carrying it. A single back injury claim from an employee lifting a pressure washer onto a truck bed can run into six figures. The premium is almost always cheaper than the alternative.
Commercial Auto Insurance for Mobile Service Rigs
Your trucks and trailers are your business. They carry your equipment to every job, and they're on the road constantly. Texas requires minimum auto liability, but those state minimums are dangerously low for a commercial vehicle hauling a trailer loaded with pressure washers, chemical tanks, and hose reels.
Many carriers now
require underlying commercial auto limits of $500,000 to $1 million before they'll write umbrella or excess coverage. If you're planning to add an umbrella policy down the line (and you should), start with higher auto limits from day one. Also consider hired and non-owned auto coverage if any employee ever uses a personal vehicle for business errands, even a quick parts run to the supply store.
By: Linda Dodson
Agency Director at
Denton Business Insurance
Specialized Coverage for Exterior Cleaning Risks
The core policies handle the broad strokes, but pressure washing creates specific risks that require targeted endorsements or standalone policies. Skip these and you'll have coverage that looks complete on paper but fails when you need it most.
Care, Custody, and Control Endorsements
Here's a scenario that catches franchise owners off guard: you're cleaning a client's patio furniture that they asked you to move, and your crew accidentally drops a $3,000 teak table. Standard GL excludes property in your "care, custody, or control," meaning items you're temporarily responsible for during a job.
A care, custody, and control (CCC) endorsement fills this gap. For pressure washing, this matters constantly. You're moving planters, handling outdoor fixtures, and working around vehicles in driveways. The endorsement typically adds a modest amount to your premium but covers a category of claims that comes up more often than most owners expect.
Inland Marine Insurance for Pressure Washing Equipment
Your pressure washers, surface cleaners, hose reels, and chemical injection systems don't stay in one location. They travel with you daily, which means a standard commercial property policy (designed for stuff that stays in a building) won't cover them properly.
Inland marine insurance protects mobile equipment and tools wherever they go: on the truck, at a job site, or in a storage unit. Industry experts recommend insuring equipment at replacement cost rather than depreciated value. A three-year-old hot water pressure washer might have a book value of $2,000, but replacing it costs $6,000. Replacement cost coverage keeps you working after a theft or loss instead of scrambling to fund a new purchase.
Pollution Liability for Chemical Runoff and Detergents
Pressure washing generates wastewater. That wastewater contains detergents, degreasers, and whatever contaminants you just blasted off a surface: oil, paint, mildew treatments. When it flows into storm drains, you're potentially violating EPA and Texas Commission on Environmental Quality regulations.
Standard GL policies exclude pollution-related claims. A pollution liability policy covers cleanup costs, regulatory fines, and third-party claims from chemical runoff. This isn't theoretical: Texas municipalities have gotten more aggressive about enforcing stormwater regulations, and a single violation can result in fines that dwarf the cost of the policy. If you're using sodium hypochlorite, potassium hydroxide, or any commercial-grade cleaning chemical, this coverage is essential.
Comparing Basic vs. Comprehensive Franchise Protection
The difference between a bare-minimum policy and proper coverage is stark. Here's how they compare:
| Coverage Area | Basic Package | Comprehensive Package |
|---|---|---|
| General Liability | $1M/$2M, standard exclusions | $1M/$2M with "Your Work" and CCC endorsements |
| Workers' Comp | State minimum or none | Full coverage with employer's liability |
| Commercial Auto | State minimum | $500K-$1M combined single limit |
| Inland Marine | Not included | Replacement cost for all mobile equipment |
| Pollution Liability | Not included | Included for chemical runoff |
| Cyber Liability | Not included | $1M coverage for data breach |
| Umbrella | Not included | $1M-$2M excess layer |
The basic package might save you $2,000-$3,000 per year. But one uncovered claim from any of those missing categories can cost ten times that amount. Franchise owners who work with an independent agency like Denton Business Insurance can compare quotes across carriers like Nationwide, Travelers, and Chubb to build comprehensive coverage without overpaying.
Meeting Franchise Disclosure Document (FDD) Standards
Your franchisor's FDD isn't a suggestion list. It's a contractual obligation, and failing to meet its insurance requirements can put your franchise agreement at risk.
Minimum Liability Limits Required by Franchisors
Most pressure washing franchisors require GL limits of at least $1M per occurrence and $2M aggregate, but some set the bar higher for franchisees working on commercial properties. Your FDD will spell out exact requirements for every coverage type, and these often exceed what you'd buy on your own. Review the insurance section of your FDD before shopping for policies, not after.
Adding the Franchisor as an Additional Insured
Nearly every franchisor requires being listed as an additional insured on your GL policy. This gives them coverage under your policy if a claim arising from your operations names them as a defendant. Your insurance carrier issues a certificate of insurance (COI) reflecting this, and your franchisor will want to see it before you start operating. Some franchisors also require additional insured status on your commercial auto and umbrella policies. Ask your agent to review the FDD language carefully, because getting this wrong can delay your launch.
Common Questions for New Texas Franchisees
Do I need cyber liability insurance for a pressure washing business? Yes, if you process credit card payments, store customer data, or use scheduling software with client information. Small businesses with under $1M in revenue typically pay between $1,200 and $2,400 annually for $1M in standalone cyber coverage. A data breach notification alone can cost thousands.
Can I use my personal auto insurance for my work truck? No. Personal auto policies exclude commercial use. If you're hauling equipment to job sites, you need a commercial auto policy. Using personal coverage for business purposes can result in a denied claim.
What happens if I skip workers' comp in Texas? You lose key legal defenses if an employee sues you for a workplace injury. You also risk violating your franchise agreement, since most franchisors require it regardless of Texas law.
How often do I need to update my insurance certificates? Most franchisors require updated COIs annually at renewal. Some require updates whenever you add vehicles, hire employees, or change coverage limits. Set calendar reminders so you don't lapse.
Is a business owner's policy (BOP) enough for a pressure washing franchise? A BOP bundles GL and commercial property, which is a good start. But it won't include commercial auto, workers' comp, pollution liability, or inland marine. Think of a BOP as a foundation, not a complete solution.
Before You Buy a Policy
Getting insurance right for a Texas pressure washing franchise means understanding that your risks are specific and your franchisor's requirements are non-negotiable. The combination of mobile equipment, chemical usage, work on other people's property, and a crew operating powerful machinery creates a risk profile that demands more than a generic small-business policy.
Start by reading your FDD's insurance section line by line. Then work with an independent agency that understands both franchise requirements and pressure washing exposures. At Denton Business Insurance, we compare carriers across the Texas market to match coverage to your actual operations, not just check boxes on a form. If you're launching a franchise or suspect your current coverage has gaps, reach out for a policy review before the next job hits a snag.
Straight from the Clients We Serve
Texas Business Owners Rate Us 5 Stars — Here Is Why
We hear the same things repeatedly: fast service, honest advice, and coverage that made sense for their situation. That is what we aim for every time.
Protection Across Every Area of Your BUSINESS
What Texas Businesses Need. What We Deliver.
From your job site and your fleet to your data and your payroll — we cover the risks that Texas businesses carry every day.
General Liability
Covers third-party claims of bodily injury, property damage, and advertising injury. A foundational protection for nearly every Texas business, regardless of industry or size.
Commercial Property
Covers your building, equipment, inventory, and business contents against fire, theft, storms, and vandalism. Can also include lost income if your businesses are forced to stop.
Commercial Auto
Protects vehicles your company owns, leases, or uses for work. Covers liability, collision damage, and injuries for employees driving on company time.
Errors & Omissions
Protects service providers when a client claims your advice, work, or recommendations caused them a financial loss. Critical for consultants, IT firms, agents, and other professional service businesses.
Directors & Officers
Covers leadership decisions that result in claims from employees, investors, or outside parties. Protects your directors and officers personally when management decisions are challenged.
Inland Marine & Equipment Floater
Covers tools, materials, and equipment that move between job sites or are stored off your primary property. Fills the gap where a standard commercial property policy stops.
Every Sector Has Its Own Risk Profile
We Know Your Trade. We Know Your Exposure.
We work with a wide range of Texas industries — each with different coverage priorities. Below are the sectors we serve most often.
Apartment Complexes
Texas apartment owners face liability across common areas, tenant incidents, and on-site staff. We cover your property, your income, and your exposure — across one complex or an entire portfolio.
Manufacturing Businesses
Equipment breakdowns, product liability, and workforce injuries are daily risks for Texas manufacturers. We build coverage from the shop floor to the loading dock — so one incident does not shut you down.
Artisan Contractors
Plumbers, electricians, and skilled tradespeople work in high-risk environments every day. We build coverage around your tools, your vehicles, and your crew — so a job site incident does not stop your business.
Restaurants & Food Service
Restaurants carry liability on every shift — from the kitchen to the dining room and everything in between. We protect your location, your staff, and your equipment, including lost income when operations stop.
Non-Profits Service
Non-profits face unique liability across events, volunteers, staff, and leadership decisions. We cover your organization from the ground up — so you can focus on your mission, not your exposure.
Event Insurance
Event organizers face liability the moment guests arrive, vendors set up, and alcohol is served. We cover your event from start to finish — so one unexpected incident does not cancel everything you planned for.
Answers Before You Pick Up the Phone
What Texas Businesses Ask Us Most
We get a lot of the same questions from business owners across Texas. Here are honest answers to the ones that come up most.
What information do you need to get a commercial insurance quote?
We keep the process straightforward. We typically need your business name, a description of your operations, your gross annual sales projection, number of full-time and part-time employees, your gross annual payroll, and the types of coverage you are looking for. If you have an existing policy, the expiration date and current carrier help us put together a competitive comparison.
The most important thing you can do is be transparent about what your business actually does. Accurate classification ensures you have real coverage if a claim occurs. We have seen businesses with active policies that were incorrectly classified — and those gaps only surface at the worst possible moment.
Does Texas require businesses to carry Workers' Compensation Insurance?
Texas is the only state in the country that does not require most private employers to carry Workers' Compensation. However, if your business holds government contracts or works as a subcontractor on a job site, the hiring company will almost always require proof of coverage before work begins. A growing number of general contractors across Denton and the DFW area enforce this as a standard condition.
Even without a legal requirement, carrying Workers' Comp protects your business from direct liability if an employee is hurt on the job. Medical bills, lost wages, and legal fees can add up quickly — and one serious incident can create a financial loss that far exceeds years of premium payments.
What is a commercial insurance audit and should I expect one?
Most commercial general liability policies are auditable. At the end of your policy term, the insurance carrier reviews your actual gross sales to make sure your premium matched your real exposure. If your sales grew during the year, you may owe an additional premium. If sales came in lower, you could receive a refund.
The best way to avoid a large balance due at audit time is to update your projected gross sales with us during the year if your business grows faster than expected. We can endorse your policy mid-term to reflect the change and spread any additional premium across smaller installments instead of one lump sum at year-end.
What factors affect how much my commercial coverage will cost?
Your premium is calculated based on several variables specific to your operation — industry classification, gross annual sales, number of employees, gross payroll, claims history, and the types of coverage you need. A business that handles physical work with a crew on job sites will pay differently than a professional services firm working out of an office.
As an independent agency, we compare quotes across multiple carriers — including Travelers, The Hartford, Chubb, AmTrust, and others — to find the combination of coverage and price that works for your situation. There is no obligation after your quote, and we walk through every option in plain terms before you decide anything.
My business is a restaurant — what coverage do I actually need?
Restaurants are not a one-size-fits-all class of risk. Carriers look at a range of factors when evaluating a restaurant account: whether you serve alcohol, whether deep frying is involved, the type of fire suppression system in place, whether you have a hood cleaning contract, and whether you offer catering, delivery, or live entertainment. All of these affect both pricing and carrier appetite.
A well-structured restaurant policy typically includes general liability, building and business personal property coverage, liquor liability if applicable, food contamination coverage, business income protection, and workers' compensation for your staff. We work with carriers that actively want to write restaurant accounts in Texas — including Travelers, The Hartford, and Chubb — so you have real options to compare.
Can you help insure a business that is hard to place or outside the mainstream?
Yes — this is one of our strengths. We work with Excess and Surplus (E&S) lines markets through carriers like Burns & Wilcox for businesses that standard carriers will not write. We have placed coverage for master sign electricians, cable splicing operations, transmission rebuild shops for classic cars, CBD retailers, and many other non-standard accounts.
If you have been told your business is difficult to insure or you have received very limited options in the marketplace, reach out to us. We take time to understand your operations in detail, present your account to the right markets, and work to find coverage that actually reflects what you do — not a generic policy that leaves gaps.
Still have Question?
We’re here to help you!
Written for the Texas Business Owner
Insights That Help You Make Smarter Decisions
We publish articles on real topics that affect how Texas operators get covered — from local regulatory updates to coverage gaps most owners do not know they have.
Contact Us