Texas Fire Protection Contractor Insurance

See How We're Different
Call Us: (940) 268-5112
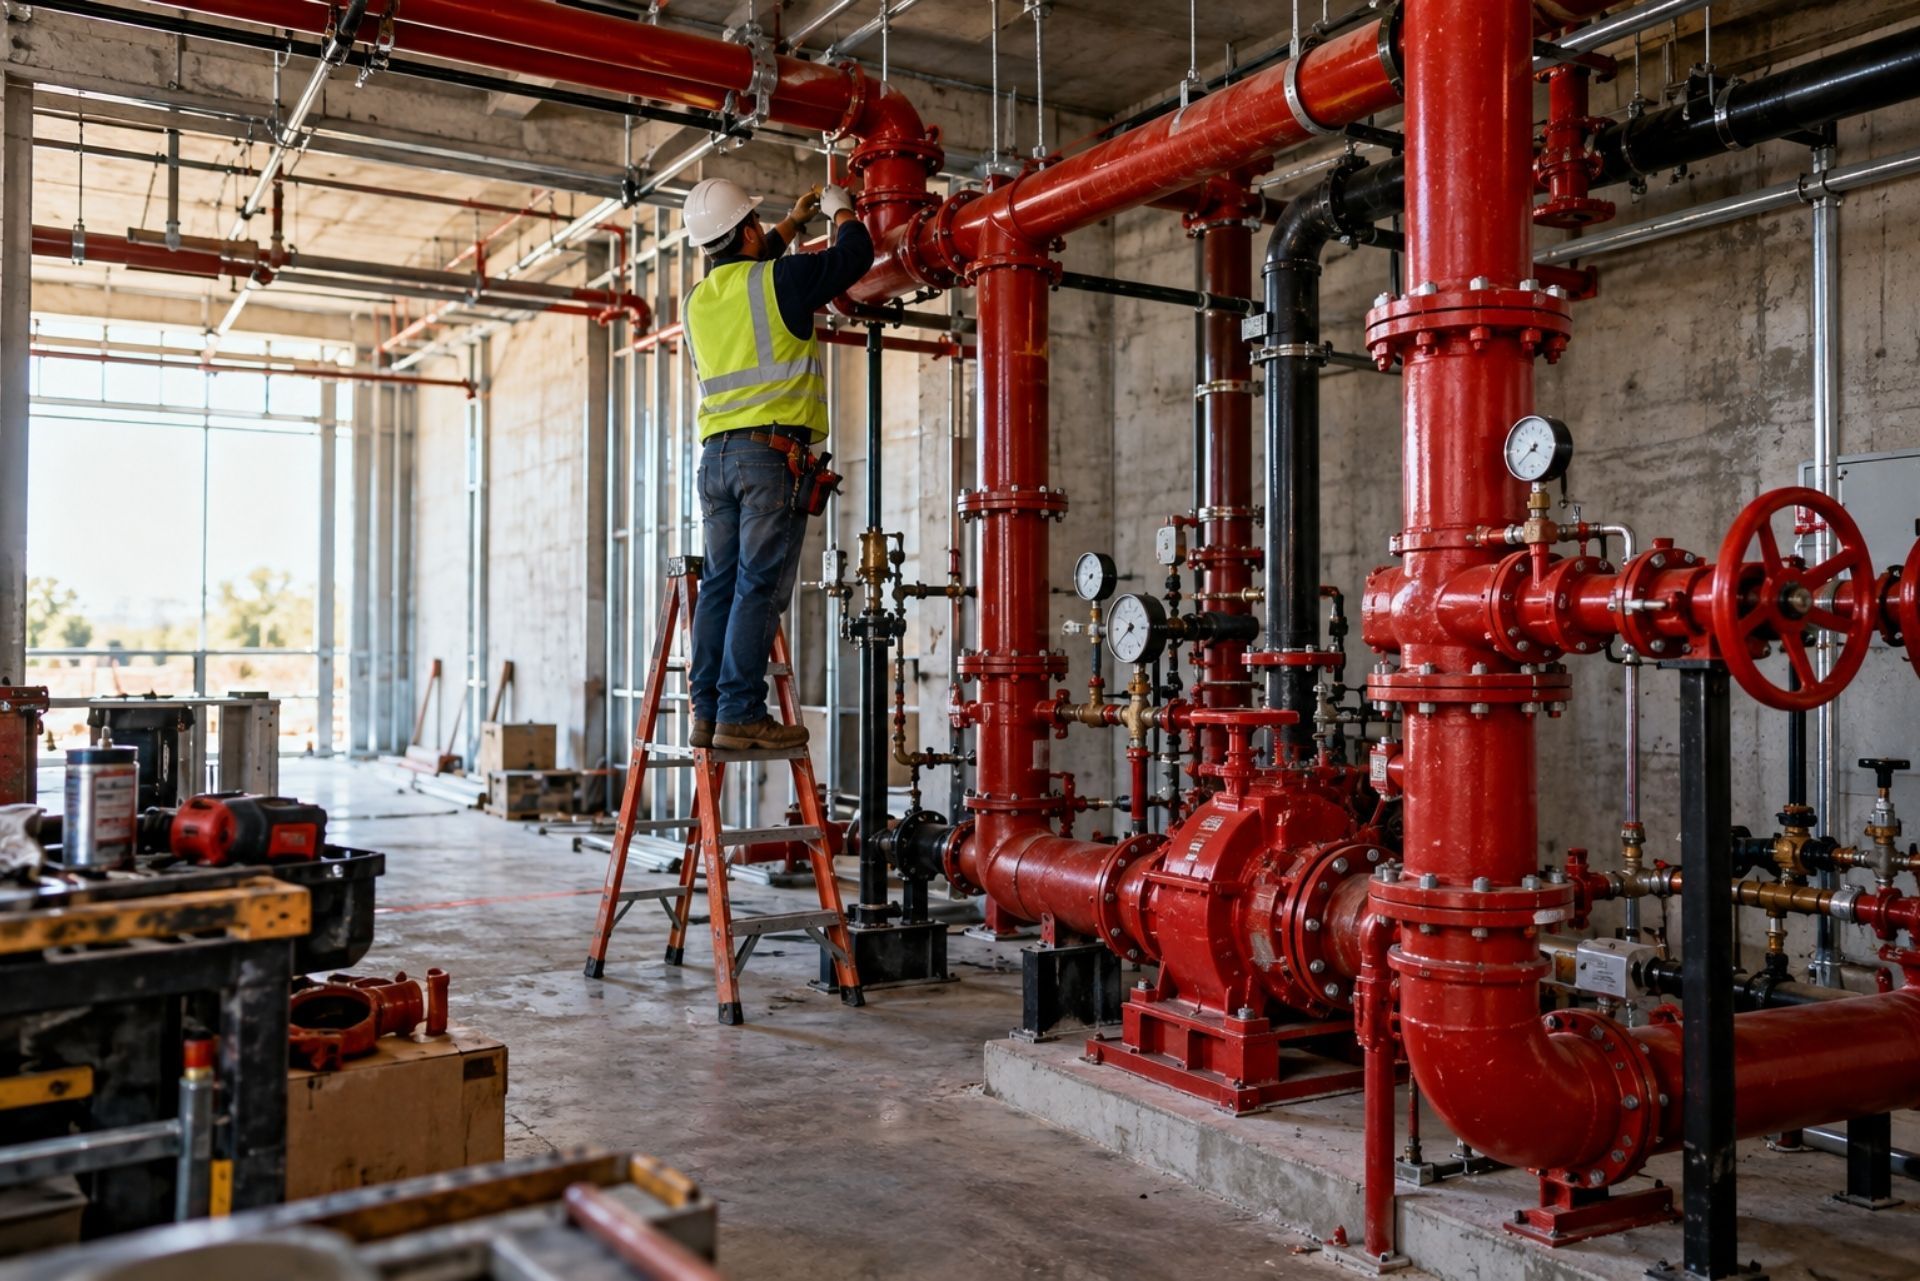
A sprinkler head malfunctions during a routine inspection at a Dallas warehouse, flooding three floors of inventory. The building owner's attorney sends a demand letter before the water is even cleaned up. If you're the fire protection contractor on that job, the next 48 hours depend entirely on what insurance you carry, and whether your policy actually covers the work you performed.
Texas fire protection contractors face a unique combination of risks: chemical exposure, system failures during real emergencies, expensive mobile equipment, and increasingly connected smart fire systems. Figuring out what insurance a fire protection contractor in Texas actually needs, from liability and property coverage to auto, cyber, and workers' compensation policies, is not as straightforward as grabbing a
general liability quote online. The wrong coverage, or the wrong exclusion buried on page 14 of your policy, can put your entire business at risk. Here's what you should actually know.
Core Insurance Requirements for Texas Fire Protection Firms
Fire protection work in Texas sits at an interesting crossroads. You're licensed through the State Fire Marshal's Office, you're working on life-safety systems, and you're often subcontracting under general contractors who have their own insurance requirements for you. That creates layers of coverage needs that go well beyond a basic policy.
Texas State Fire Marshal Licensing and Liability Minimums
The Texas Department of Insurance and the State Fire Marshal's Office require fire protection contractors to carry proof of insurance as part of their licensing. Your license type, whether you're installing fire sprinkler systems, fire alarm systems, or both, determines the specifics. Most licensing categories require a minimum of $100,000 combined single limit per occurrence and $300,000 aggregate for the policy year, including products and completed operations coverage (https://d2l2jhoszs7d12.cloudfront.net/state/Texas/Texas Insurance/httpwww.tdi.texas.govformsformlisting.html/Forms/sf239insrequire.pdf).
Don't confuse the licensing minimum with adequate protection. The state's floor is just that: a floor. A single water damage claim from a failed sprinkler tie-in can exceed minimum limits before the adjuster even finishes the inspection.
General Liability vs. Professional Liability (Errors and Omissions)
General liability (GL) covers bodily injury and property damage caused by your operations. If a technician drops a pipe fitting on someone's foot, GL responds. But GL has limits when it comes to design errors, incorrect system specifications, or a fire suppression system that was installed to code but simply didn't work as intended.
That's where professional liability, also called errors and omissions (E&O), fills the gap. If you're designing fire suppression layouts, specifying equipment, or signing off on system adequacy, E&O coverage protects you against claims that your professional judgment was faulty. Many fire protection firms carry both, and for good reason: the line between "your installer broke something" and "your engineer designed it wrong" gets blurry fast in litigation.
Workers' Compensation Laws in the Lone Star State
Texas stands alone as the only state where private employers can opt out of workers' compensation as a non-subscriber. That sounds like a cost-saving opportunity, and some contractors treat it that way. But going without workers' comp in fire protection work is a gamble with steep odds.
Non-subscribers lose key legal defenses if an employee is injured on the job. You can't argue contributory negligence, and you can't cap damages. For a trade where technicians climb ladders, handle pressurized systems, and work with chemical suppression agents, the exposure is real. Most general contractors also require proof of workers' comp before allowing subs on-site, so opting out can cost you contracts.
By: Linda Dodson
Agency Director at
Denton Business Insurance
Specialized Coverage for Fire Sprinkler and Alarm Contractors
Standard commercial policies are built for general contractors, not for the specific hazards fire protection work creates. Two coverage types stand out as particularly important for this trade.
Pollution Liability for Chemical Suppression Systems
If your work involves clean agent systems, foam suppression, or any chemical-based fire suppression, you need pollution liability coverage. A leak or accidental discharge of suppression chemicals can trigger environmental cleanup obligations, and standard GL policies almost universally exclude pollution events.
This is especially relevant for contractors servicing industrial facilities, data centers, or commercial kitchens where specialized suppression agents are common. A single clean agent discharge in a server room can create tens of thousands of dollars in cleanup and equipment replacement costs.
Completed Operations and Efficacy Insurance
Completed operations coverage is part of your GL policy, but you need to make sure it's not excluded or sublimited. This coverage responds after you've finished a job and left the site. If a sprinkler system you installed six months ago fails and causes water damage, completed operations is what pays.
Efficacy insurance goes a step further. It covers you if your fire protection system fails to perform its intended function during an actual emergency. This is a specialized product, and not every carrier offers it, but for contractors installing life-safety systems, it addresses the most catastrophic scenario: a fire breaks out, your system doesn't suppress it, and someone gets hurt or property is destroyed.
Comparison of Standard vs. Specialized Fire Protection Policies
Table: Comparison of Coverage Gaps and Protection Levels
| Coverage Type | Standard Commercial Policy | Specialized Fire Protection Policy |
|---|---|---|
| General Liability | Included; may have low sublimits | Higher limits; tailored to fire protection ops |
| Completed Operations | Often sublimited or excluded | Full coverage for post-installation claims |
| Efficacy Coverage | Not included | Available as endorsement or standalone |
| Pollution Liability | Excluded | Available for chemical suppression work |
| Professional Liability (E&O) | Not included | Available for design/engineering services |
| Inland Marine | Not included | Covers tools and equipment in transit |
| Cyber Liability | Rarely included | Covers smart system and data breach risks |
The gap between a generic policy and one built for fire protection work is significant. A contractor who only carries standard GL is exposed on multiple fronts, particularly completed operations and pollution events.
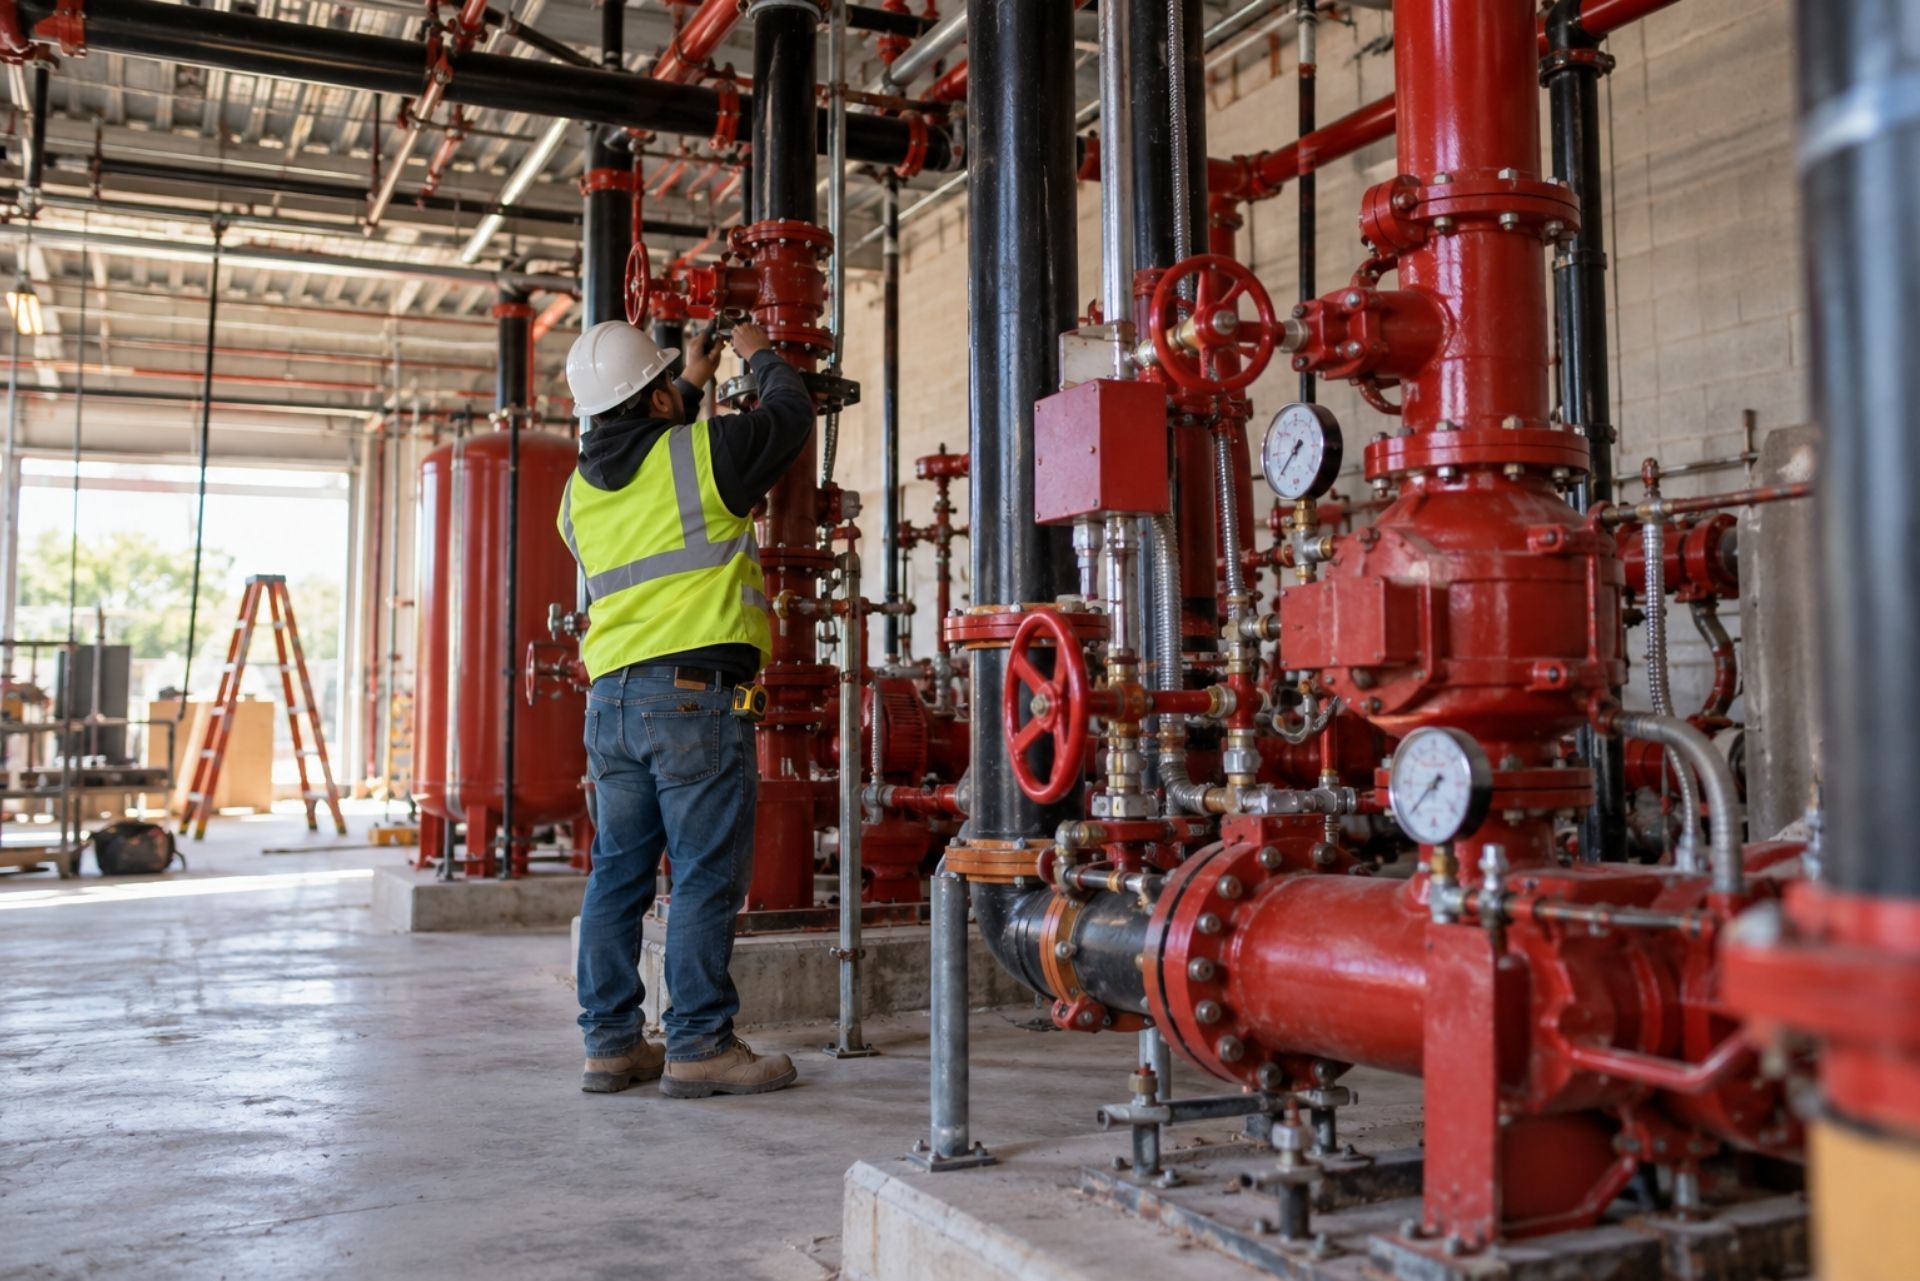
Managing Risk During Installation and Inspections
Fire protection contractors spend a lot of time on the road and increasingly rely on connected technology. Both of those realities create insurance needs that are easy to overlook.
Commercial Auto and Inland Marine for Mobile Equipment
Your service vans, pipe threaders, testing equipment, and specialized tools are the backbone of your operation. Commercial auto insurance covers your vehicles, but standard property insurance does not cover tools or equipment while they are in transit. That's the gap inland marine insurance fills.
If a van full of backflow preventers and testing gauges gets stolen from a job site parking lot, your commercial property policy won't pay for the contents. Inland marine covers tools, equipment, and materials whether they're on a truck, at a job site, or in temporary storage. For Texas fire protection contractors who move between multiple sites daily, this coverage is essential.
Texas minimum auto liability limits are $30,000/$60,000/$25,000 (https://www.billtrack50.com/billdetail/1858169), but those minimums won't go far if your service vehicle causes a serious accident. Most contractors carry at least $500,000 in combined single limit coverage, and an umbrella policy on top of that is common.
Cyber Liability for Integrated Smart Fire Systems
This is the coverage most fire protection contractors don't think they need, until they do. Modern fire alarm and suppression systems are networked, cloud-monitored, and integrated with building management systems. If your company manages monitoring accounts, stores client data, or connects to building networks during installation, you have cyber exposure.
Cyber insurance carriers in 2026 have moved beyond simple application questionnaires. They now use technical underwriting with outside-in scans to verify your security controls before issuing a policy. If you're running outdated software on your diagnostic laptops or using default passwords on networked fire panels, expect pushback from underwriters.
A data breach involving client building layouts, access codes, or system vulnerabilities isn't just an IT problem. It's a liability problem. Cyber coverage handles breach notification costs, legal defense, and regulatory fines.
Common Questions About Texas Fire Contractor Insurance
Do I need insurance if I only do fire extinguisher inspections? Yes. Even a routine inspection carries liability if the extinguisher fails during a fire and someone argues your inspection was negligent. A basic GL policy is the minimum, and most clients will require a certificate of insurance before letting you on-site.
What is "efficacy" coverage and why do I keep hearing about it? Efficacy insurance protects you if a fire system you installed or serviced fails to perform its intended function during an actual emergency. Standard GL covers damage your work causes, but efficacy covers the failure of your work to prevent damage. It's a critical distinction for life-safety contractors.
How much does a typical policy cost for a Texas startup? Small fire protection crews with 2 to 5 employees can expect annual commercial general liability premiums between $780 and $1,900, while mid-sized operations with 6 to 15 employees typically see costs ranging from $1,900 to $5,000. Workers' comp, auto, and specialty coverages add to that baseline. Your specific services, payroll size, and claims history all affect pricing.
Does my General Liability cover damage from accidental sprinkler discharge? It might, but don't assume. Many standard GL policies have water damage exclusions or require a specific endorsement for damage resulting from your sprinkler work. Ask your agent to walk you through the exclusions section of your policy. If the words "water damage" appear near the word "excluded," you need a conversation.
Can I use one policy for both fire alarms and fire sprinklers? Yes, a single GL policy can cover both operations. The key is making sure your agent lists both classifications on the policy so the carrier understands the full scope of your work. If you're rated only for alarm installation but you're also running sprinkler pipe, you could face a claim denial. At Denton Business Insurance, we see this mistake regularly with contractors who started in one specialty and expanded without updating their coverage.
Making the Right Choice for Your Business
Fire protection contractors in Texas carry a responsibility that most trades don't: your work has to perform flawlessly when lives are on the line. Your insurance should reflect that reality. Texas construction businesses that stay proactive, document their risk controls, and invest in technology consistently secure better pricing from carriers, so building good habits now pays off at every renewal.
The right insurance program for a fire protection contractor isn't a single policy. It's a combination of GL, professional liability, workers' comp, commercial auto, inland marine, and potentially cyber and efficacy coverage, all structured to match your specific operations. Getting this wrong leaves gaps that only become visible during a claim, which is the worst possible time to discover them.
Denton Business Insurance works with fire protection contractors across Texas, comparing quotes from carriers like Nationwide, Travelers, and Chubb to build coverage that actually matches the work you do. If you're unsure whether your current policy covers completed operations, chemical suppression risks, or your fleet of service vehicles, that's worth a phone call. Getting the right coverage in place before the next job starts is the smartest risk management decision you can make.
Straight from the Clients We Serve
Texas Business Owners Rate Us 5 Stars — Here Is Why
We hear the same things repeatedly: fast service, honest advice, and coverage that made sense for their situation. That is what we aim for every time.
Protection Across Every Area of Your BUSINESS
What Texas Businesses Need. What We Deliver.
From your job site and your fleet to your data and your payroll — we cover the risks that Texas businesses carry every day.
General Liability
Covers third-party claims of bodily injury, property damage, and advertising injury. A foundational protection for nearly every Texas business, regardless of industry or size.
Commercial Property
Covers your building, equipment, inventory, and business contents against fire, theft, storms, and vandalism. Can also include lost income if your businesses are forced to stop.
Commercial Auto
Protects vehicles your company owns, leases, or uses for work. Covers liability, collision damage, and injuries for employees driving on company time.
Errors & Omissions
Protects service providers when a client claims your advice, work, or recommendations caused them a financial loss. Critical for consultants, IT firms, agents, and other professional service businesses.
Directors & Officers
Covers leadership decisions that result in claims from employees, investors, or outside parties. Protects your directors and officers personally when management decisions are challenged.
Inland Marine & Equipment Floater
Covers tools, materials, and equipment that move between job sites or are stored off your primary property. Fills the gap where a standard commercial property policy stops.
Every Sector Has Its Own Risk Profile
We Know Your Trade. We Know Your Exposure.
We work with a wide range of Texas industries — each with different coverage priorities. Below are the sectors we serve most often.
Apartment Complexes
Texas apartment owners face liability across common areas, tenant incidents, and on-site staff. We cover your property, your income, and your exposure — across one complex or an entire portfolio.
Manufacturing Businesses
Equipment breakdowns, product liability, and workforce injuries are daily risks for Texas manufacturers. We build coverage from the shop floor to the loading dock — so one incident does not shut you down.
Artisan Contractors
Plumbers, electricians, and skilled tradespeople work in high-risk environments every day. We build coverage around your tools, your vehicles, and your crew — so a job site incident does not stop your business.
Restaurants & Food Service
Restaurants carry liability on every shift — from the kitchen to the dining room and everything in between. We protect your location, your staff, and your equipment, including lost income when operations stop.
Non-Profits Service
Non-profits face unique liability across events, volunteers, staff, and leadership decisions. We cover your organization from the ground up — so you can focus on your mission, not your exposure.
Event Insurance
Event organizers face liability the moment guests arrive, vendors set up, and alcohol is served. We cover your event from start to finish — so one unexpected incident does not cancel everything you planned for.
Answers Before You Pick Up the Phone
What Texas Businesses Ask Us Most
We get a lot of the same questions from business owners across Texas. Here are honest answers to the ones that come up most.
What information do you need to get a commercial insurance quote?
We keep the process straightforward. We typically need your business name, a description of your operations, your gross annual sales projection, number of full-time and part-time employees, your gross annual payroll, and the types of coverage you are looking for. If you have an existing policy, the expiration date and current carrier help us put together a competitive comparison.
The most important thing you can do is be transparent about what your business actually does. Accurate classification ensures you have real coverage if a claim occurs. We have seen businesses with active policies that were incorrectly classified — and those gaps only surface at the worst possible moment.
Does Texas require businesses to carry Workers' Compensation Insurance?
Texas is the only state in the country that does not require most private employers to carry Workers' Compensation. However, if your business holds government contracts or works as a subcontractor on a job site, the hiring company will almost always require proof of coverage before work begins. A growing number of general contractors across Denton and the DFW area enforce this as a standard condition.
Even without a legal requirement, carrying Workers' Comp protects your business from direct liability if an employee is hurt on the job. Medical bills, lost wages, and legal fees can add up quickly — and one serious incident can create a financial loss that far exceeds years of premium payments.
What is a commercial insurance audit and should I expect one?
Most commercial general liability policies are auditable. At the end of your policy term, the insurance carrier reviews your actual gross sales to make sure your premium matched your real exposure. If your sales grew during the year, you may owe an additional premium. If sales came in lower, you could receive a refund.
The best way to avoid a large balance due at audit time is to update your projected gross sales with us during the year if your business grows faster than expected. We can endorse your policy mid-term to reflect the change and spread any additional premium across smaller installments instead of one lump sum at year-end.
What factors affect how much my commercial coverage will cost?
Your premium is calculated based on several variables specific to your operation — industry classification, gross annual sales, number of employees, gross payroll, claims history, and the types of coverage you need. A business that handles physical work with a crew on job sites will pay differently than a professional services firm working out of an office.
As an independent agency, we compare quotes across multiple carriers — including Travelers, The Hartford, Chubb, AmTrust, and others — to find the combination of coverage and price that works for your situation. There is no obligation after your quote, and we walk through every option in plain terms before you decide anything.
My business is a restaurant — what coverage do I actually need?
Restaurants are not a one-size-fits-all class of risk. Carriers look at a range of factors when evaluating a restaurant account: whether you serve alcohol, whether deep frying is involved, the type of fire suppression system in place, whether you have a hood cleaning contract, and whether you offer catering, delivery, or live entertainment. All of these affect both pricing and carrier appetite.
A well-structured restaurant policy typically includes general liability, building and business personal property coverage, liquor liability if applicable, food contamination coverage, business income protection, and workers' compensation for your staff. We work with carriers that actively want to write restaurant accounts in Texas — including Travelers, The Hartford, and Chubb — so you have real options to compare.
Can you help insure a business that is hard to place or outside the mainstream?
Yes — this is one of our strengths. We work with Excess and Surplus (E&S) lines markets through carriers like Burns & Wilcox for businesses that standard carriers will not write. We have placed coverage for master sign electricians, cable splicing operations, transmission rebuild shops for classic cars, CBD retailers, and many other non-standard accounts.
If you have been told your business is difficult to insure or you have received very limited options in the marketplace, reach out to us. We take time to understand your operations in detail, present your account to the right markets, and work to find coverage that actually reflects what you do — not a generic policy that leaves gaps.
Still have Question?
We’re here to help you!
Written for the Texas Business Owner
Insights That Help You Make Smarter Decisions
We publish articles on real topics that affect how Texas operators get covered — from local regulatory updates to coverage gaps most owners do not know they have.
Contact Us